Momentum vs Mean Reversion Strategies for Challenges
Momentum vs mean reversion, decided by three numbers: ADX, ATR percentile and Hurst. Regime-switch thresholds, stop logic, expectancy maths and prop-challenge rules.
By Marcel Hambálek · Senior Trader, For Traders
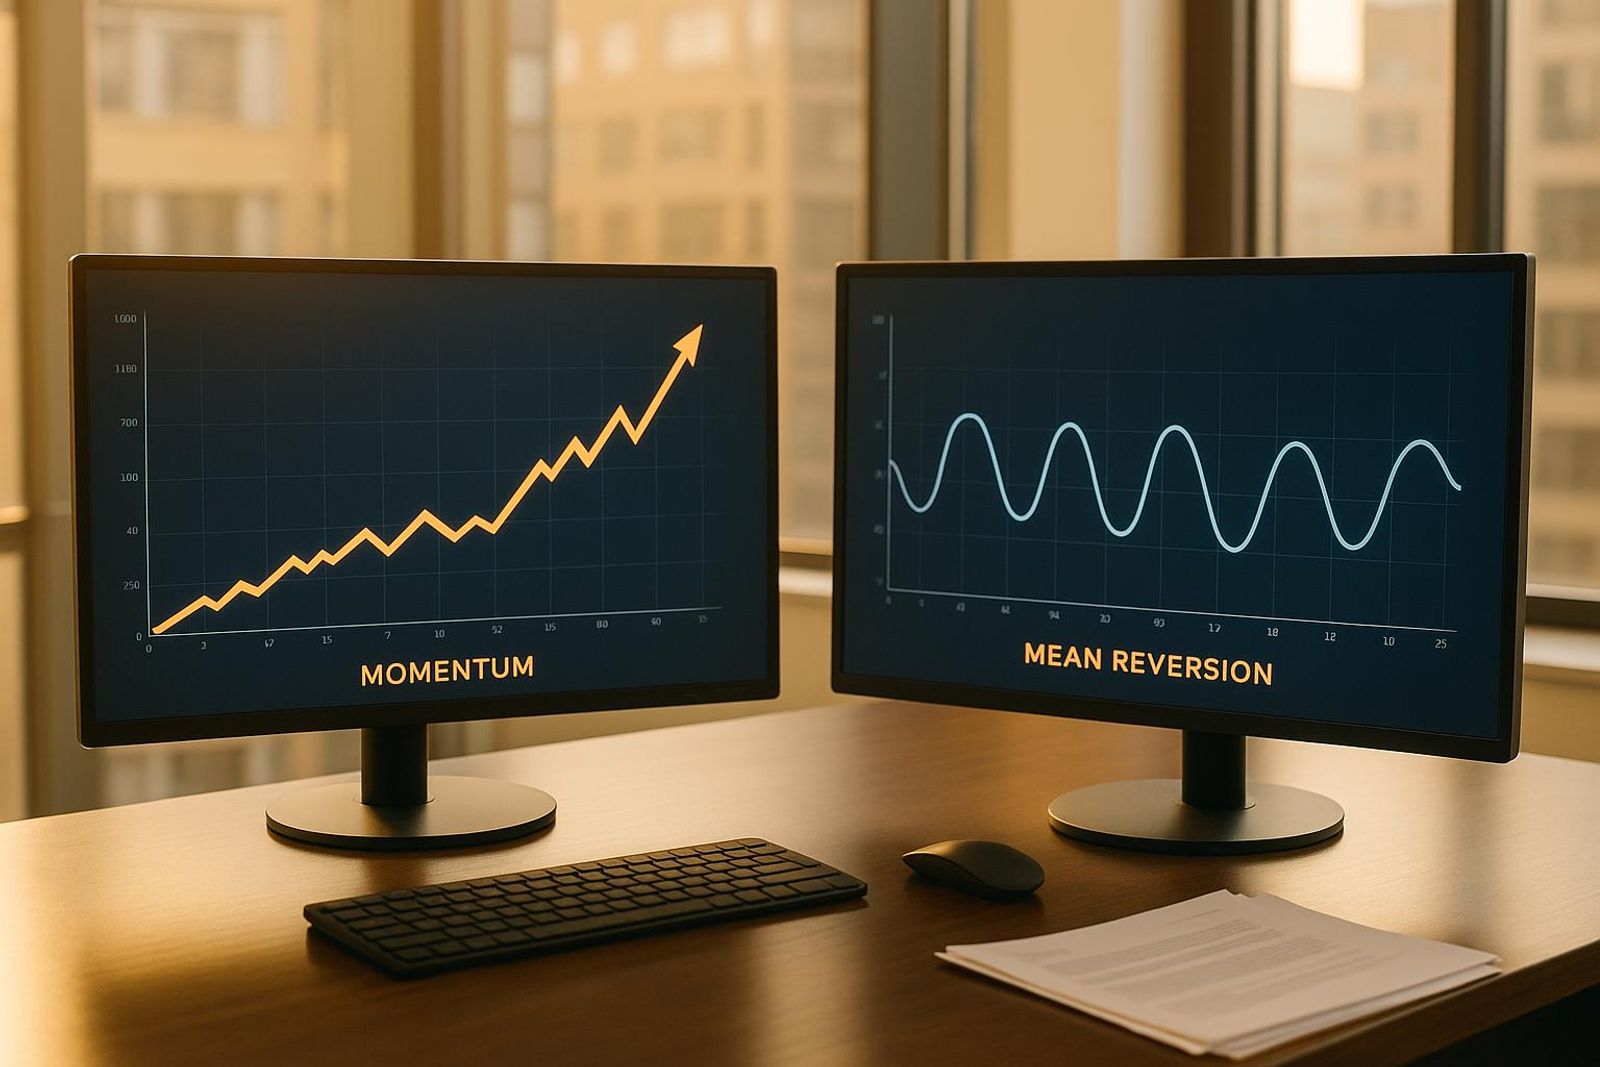
Momentum buys strength and mean reversion buys distance from a mean — and three numbers decide which one you run today: ADX above 25 with ATR in the top 40% of its 100-day range favours momentum; ADX below 20 with ATR in the bottom 40% and a Hurst exponent under 0.45 favours mean reversion. Between those bands, trade neither.
Key takeaways
- Momentum ranks and rides strength; mean reversion measures distance from a mean and bets on the snap-back — they are opposite bets on the same price series, so the regime, not preference, picks the winner.
- Use three measurable filters before the first trade of the session: ADX (trend strength), ATR percentile (volatility regime) and Hurst exponent or variance ratio (persistence vs anti-persistence).
- Mean reversion typically wins 60-75% of trades at 0.5-1R; momentum wins 35-45% at 2-4R — the expectancy can be identical, but the psychology and drawdown shape are not.
- Unstopped RSI fades are the single fastest way to fail a 5% max drawdown evaluation: one blown range can erase forty small wins.
- A momentum trap has three observable tells before you get filled at the extreme — volume divergence, ATR stretched 2×+ beyond its average leg, and a failed retest of the breakout level.
- Regime switching needs hysteresis and confirmation bars; flipping modes on a single bar turns two working strategies into one whipsaw machine.
Watch: related video
The verdict: momentum or mean reversion today, in three numbers
Momentum trades the continuation of a move already in progress. Mean reversion trades the distance between price and a reference mean, betting that distance snaps back. Neither is the "better" strategy family — both produce positive expectancy in the right regime and bleed you dry in the wrong one. The job isn't picking a side once; it's reading three numbers before you place size on either.
The one-sentence difference
If momentum asks "how far can this run," mean reversion asks "how far has this stretched, and when does the rubber band snap back." That's the whole momentum vs mean reversion debate distilled — one edge harvests continuation, the other harvests overextension. Both edges decay the moment you apply them outside their regime, which is why "mean reversion vs trend following" is really a regime question, not a personality question.
The three-number decision (ADX, ATR percentile, Hurst)
You don't need a discretionary read on "does this look trendy." You need three inputs, checked before entry:
| Regime | ADX (14) | ATR percentile (100-period) | Hurst exponent |
|---|---|---|---|
| Momentum mode | > 25 | > 60th percentile | > 0.55 (trending) |
| Mean reversion mode | < 20 | < 40th percentile | < 0.45 (reverting) |
| No-regime zone | 20–25 | 40th–60th percentile | 0.45–0.55 |
ADX confirms trend strength, ATR percentile confirms there's enough range expansion to actually pay for continuation risk, and the Hurst exponent confirms the underlying series isn't just noise pretending to trend. Run all three on XAUUSD or US100 over a full year and you'll see momentum and mean reversion strategies each post solid expectancy — but only inside their own lane. Cross the lane and the same setup that printed for months starts handing back R.
What to do when the numbers disagree
ADX at 22 with ATR at the 50th percentile and Hurst at 0.48 isn't a signal — it's the market telling you it hasn't picked a direction yet. That's the no-regime zone, and it's wider than most traders admit, often 30-40% of trading days on an instrument like XAUUSD. Two options here, and only two:
- Cut size hard. Half your normal risk, if you trade at all, until at least two of the three numbers agree.
- Stand down. No trade is a position. Chasing a signal that doesn't exist is how a clean equity curve turns into a blown daily loss limit two days before FOMC.
Traders who pass evaluations aren't the ones who guessed right on regime more often — they're the ones who sized down or sat out when the numbers disagreed instead of forcing a trade to feel busy.
Momentum, trend following and mean reversion are three different signals
Momentum, trend following, and mean reversion are not two ideas — they're three, and mixing them up is the fastest way to put the wrong stop on the right trade. Most retail content treats momentum and trend following as synonyms. They're not. Momentum is a ranking. Trend following is a trigger. Mean reversion is a distance measurement. Each one answers a different question about price, which is exactly why each needs a different stop and a different sizing logic.
Momentum = ranking (relative strength over a lookback)
Momentum asks: what has outperformed over the last N periods? You're not waiting for an event — you're ranking assets or timeframes by return over a lookback window (20-day, 60-day, 12-month, whatever the system specifies) and buying what's already at the top of that ranking. There's no discrete trigger. A momentum signal can be "on" for weeks without a single crossover or breakout firing. The stop logic here is typically volatility-based (ATR multiple) because you're riding an established leg, not reacting to a level.
Trend following = trigger (a breakout or crossover event)
Trend following asks: has a specific level or condition just broken? This is event-driven. A Donchian channel breakout — price closing above the 20-day or 55-day high — is a trigger. So is a MACD crossover, where the fast line crosses the signal line. You're not ranking anything; you're waiting for a discrete event to fire, then acting on it. The stop sits at the invalidation of that same event — back inside the channel, or the crossover reversing.
Mean reversion = distance (deviation from a reference price)
Mean reversion asks: how far has price stretched from where it "should" be? This is a distance measurement, expressed via z-score deviation bands, Bollinger Bands, Keltner Channels, or RSI-2 extremes. You're fading distance, not chasing direction. The stop logic is structural — a further multiple of the same deviation measure — because if distance keeps expanding, your premise (reversion) is already broken.
| Signal type | What it measures | Common tools | Stop logic |
|---|---|---|---|
| Momentum | Relative strength ranking over a lookback | Rate of change, 12-month/60-day return ranking | ATR multiple trailing the leg |
| Trend following | A discrete breakout/crossover event | Donchian channel breakout, MACD crossover | Invalidation of the trigger level |
| Mean reversion | Deviation distance from a reference price | Z-score bands, Bollinger Bands, Keltner Channels, RSI-2 | Further deviation multiple, premise-based |
This is the core of the mean reversion vs trend following confusion: traders take a breakout entry (trend following) and then manage the stop like it's a momentum trade, or fade a Bollinger Band touch and set a trend-following trailing stop that never gets hit because the premise was distance, not direction. Know which of the three you actually took before you set the stop — not after.
Side-by-side: win rate, R:R, drawdown profile and challenge fit
Momentum wins less often but bigger, mean reversion wins more often but smaller, and trend following sits closer to momentum with a longer holding period — the numbers below are what actually separates a smooth equity curve from a lumpy one inside a funded evaluation.
The comparison table
| Metric | Momentum | Mean Reversion | Trend Following |
|---|---|---|---|
| Win rate | 35–45% | 60–75% | 30–40% |
| Typical R:R target | 2–4R | 0.5–1R | 3–8R+ |
| Volatility regime needed | Expanding (ATR rising) | Contracting (ATR falling) | Expanding, sustained |
| Holding period | Hours to days | Minutes to hours | Days to weeks |
| Drawdown shape | Long strings of small losses | Rare, violent single losses | Long flat periods, then one big leg |
Why the same expectancy feels completely different
Run the math and momentum and mean reversion can land on nearly identical expectancy and R-multiples — say +0.15R per trade for both — and still feel nothing alike in a trading journal. A momentum system with a 40% win rate and 3R average winner is losing six or seven trades in a row somewhere in every 100-trade sample; that's just binomial variance, not a broken edge. A mean reversion trading strategy win rate of 70% with a 0.7R target rarely strings together more than two or three losses — but when the mean doesn't hold (a trend day blows through your fade level), that single loss can run 3–4R because the stop sits past a structure level, not a tight ATR multiple.
That distinction matters more than the win rate headline. Prop firms don't grade you on how good your stats look in a spreadsheet — they grade you on max drawdown and daily loss limit breaches, which are path-dependent, not average-dependent.
Which one fits a funded evaluation timeline
This is the real answer to momentum vs mean reversion prop challenge selection: mean reversion's frequent small wins and rare-but-survivable losses produce a smoother equity curve that respects a daily loss limit — you're less likely to blow 5% in a single session because your losers are capped by tight targets even when they occasionally run wide. Momentum, by contrast, produces the outlier days — the one trade that runs 4R on a genuine breakout — that clear a 10% profit target in a fraction of the trading days a mean reversion approach needs. If your challenge rewards speed and you can stomach the losing streaks, momentum gets you there faster. If your challenge punishes a single bad day more than it punishes a slow climb, mean reversion is the one that keeps you in the game long enough to pass.
How to measure the regime before you place a trade
How do you detect a regime shift in markets before it costs you a trade? Run four checks on the same chart — ADX, ATR percentile, Hurst exponent, and half-life — and let them agree before you commit size.
ADX and ATR percentile: the two-minute check
ADX (Average Directional Index), measured over 20 periods, tells you whether a trend has enough force to trade — above 25 means momentum has teeth, below 20 means the market is chopping sideways. Pair it with a 100-day ATR percentile: if today's ATR sits in the top 40% of the last 100 days, volatility supports a breakout continuing; in the bottom 40%, it favors a snap-back. This is the fastest filter you'll run — thirty seconds on any charting platform, no spreadsheet required.
Hurst exponent and the variance ratio test
The Hurst exponent is a single number, calculated over a rolling 100-bar window, that tells you whether price persists (above 0.5, momentum regime), wanders randomly (right at 0.5), or reverts (below 0.5, mean-reversion regime). The variance ratio test backs it up from a different angle — it compares realized variance over long horizons to short ones; a ratio above 1 confirms trending behavior, below 1 confirms reversion. Run both together: a Hurst reading of 0.38 alongside a variance ratio of 0.7 is a much stronger reversion signal than either alone.
Half-life of mean reversion (Ornstein-Uhlenbeck) and how long to hold
Half-life, derived from the Ornstein-Uhlenbeck model, tells you how many bars a deviation from the mean typically takes to decay halfway back — and that number is your maximum hold time, not a guess. If your half-life reads 14 bars on the H1 chart and your trade hasn't reverted by bar 20, the regime has likely shifted underneath you and you're now holding a mean-reversion trade inside a momentum move. Cut it rather than wait for confirmation that never comes.
Volatility clustering and autocorrelation in plain language
Volatility clustering means quiet begets quiet and violent begets violent — big moves tend to follow big moves, and calm days cluster together, regardless of direction. That's why ATR percentile matters more than a single day's range. Autocorrelation and anti-autocorrelation describe the same idea from the return side: positive autocorrelation means today's move tends to repeat tomorrow (momentum's friend), negative autocorrelation means it tends to reverse (mean reversion's friend). Check autocorrelation on daily returns over the same 100-bar window you use for Hurst, and the two should tell a consistent story.
| Measure | Window | Momentum reading | Mean-reversion reading |
|---|---|---|---|
| ADX | 20 periods | Above 25 | Below 20 |
| ATR percentile | 100 days | Top 40% | Bottom 40% |
| Hurst exponent | 100 bars | Above 0.5 | Below 0.45 |
| Variance ratio | 100 bars | Above 1 | Below 1 |
| Half-life (O-U) | Rolling estimate | N/A — trend, don't time exits | Sets max hold in bars |
The regime-switching rulebook you can copy today
Direct answer: measure your regime once at session open, refresh every 4 hours, require two consecutive closes above ADX 25 to flip into momentum mode and three consecutive closes below ADX 20 to flip back to mean reversion — then halve size or stand down entirely when neither condition is met. This asymmetric hysteresis is what stops a regime detection trading strategy from whipsawing on noise instead of trading the actual shift.
Step 1: set the measurement window and refresh time
Lock your ADX, ATR percentile, and Hurst exponent calculation to a fixed schedule — session open (00:00 UTC for FX, cash open for indices) and every 4 hours after. Checking continuously invites you to react to a single noisy bar; checking too rarely means you're trading yesterday's regime with today's capital. Four hours matches the half-life of most intraday regime shifts on XAUUSD and NSDQ without over-trading the signal.
Step 2: confirmation bars and hysteresis bands
This is the part most quant trading rules for momentum mean reversion breakout systems skip entirely — a single close crossing 25 isn't confirmation, it's a coin flip.
- Momentum entry: two consecutive closes with ADX(20) > 25 AND ATR percentile in the top 40% of its 100-day range.
- Mean-reversion entry: three consecutive closes with ADX(20) < 20, ATR percentile in the bottom 40%, and Hurst exponent < 0.45.
- Exit either regime: the moment the opposite side's confirmation count starts building — don't wait for full reversal confirmation before de-risking the existing position.
The asymmetry (2 bars in, 3 bars out for momentum) is deliberate — trends decay slower than they ignite, so you give momentum more benefit of the doubt on the way out than on the way in.
| Measure | Window | Momentum reading | Mean-reversion reading |
|---|---|---|---|
| ADX | 20 periods | Above 25 | Below 20 |
| ATR percentile | 100 days | Top 40% | Bottom 40% |
| Hurst exponent | 100 bars | Above 0.5 | Below 0.45 |
| Variance ratio | 100 bars | Above 1 | Below 1 |
| Half-life (O-U) | Rolling estimate | N/A — trend, don't time exits | Sets max hold in bars |
Step 3: what to trade in the no-regime zone
ADX between 20-25, or ATR sitting in the middle 20% of its range — that's the no-regime zone, and it's where accounts bleed out slowly. Halve your standard position size or stand down completely. If you're running algorithmic trading mean reversion momentum systems into 2026, this is the state your config should default to, not an edge case you patch later.
Step 4: hard overrides — FOMC, NFP and gap opens
The first 15 minutes after FOMC and NFP prints override every regime read on your screen — that window isn't momentum or mean reversion, it's a liquidity event with spreads and slippage that make both models unreliable. Same logic applies to gap opens after a weekend or major news. Flatten discretionary regime trades, or run pre-defined breakout brackets sized for the event, not for the regime you measured four hours ago.
How a mean reversion trade actually works — and when it beats trend following
Mean reversion works by fading distance, not chasing direction: you sell stretch above a statistical mean and buy stretch below it, targeting the mean itself — not the opposite extreme. The question "is mean reversion profitable" only has a useful answer once you define the mean, the entry trigger, and the exit discipline. Get sloppy on any of those three and you're just fading trends into a bigger stop.
Choosing the mean: 20-SMA vs session VWAP
Swing traders anchor to the 20-period SMA on the daily or 4H — it's slow enough to filter noise but still tracks the underlying drift. Intraday, that anchor should be session VWAP, not a moving average. VWAP resets each session and represents the volume-weighted "fair price" that institutional flow actually transacted at — on XAUUSD and NSDQ futures, price pulls back to session VWAP with striking regularity during range days. Pick one mean per timeframe and stick with it; switching anchors mid-trade is how traders talk themselves into holding a loser.
Entry at ±1.5 to 2 z-score, exit at the mean not the far band
Define your bands using z-score deviation bands — standard deviations of price from the mean, recalculated on a rolling window. Entries trigger at 1.5 to 2 z-score away from the mean: stretched enough that reversion has statistical edge, not so extreme you're waiting for a black swan. The exit is the mean, full stop. Treat a touch of the opposite band as a bonus you trail into, never the plan you built the trade around — most mean reversion trades that "give it all back" died waiting for a target that was never the highest-probability outcome.
Where the stop goes: ±3 z-score or 1.5× ATR outside the band
Your stop belongs beyond the statistical extreme — either the ±3 z-score line or 1.5× ATR outside your entry band, whichever gives more room in that instrument's current volatility. Never anchor a stop to a round number; that's exactly where clustered retail orders sit and where a 3-sigma spike loves to tag before reverting. On a low-ATR session this stop might be tight and cheap to hold; during post-NFP chop it widens fast, which is your cue to cut size, not move the stop closer.
Combining divergence and mean reversion for a cleaner trigger
Raw z-score touches generate a lot of trades, plenty of them low quality. Two RSI variants filter that noise: RSI 2 extremes (readings under 5 or over 95) catch short-term exhaustion on lower timeframes, while RSI 14 extremes (below 30 or above 70) suit swing entries on the daily. Combining divergence and mean reversion — price making a new extreme while RSI or MACD fails to confirm it — cuts trade count meaningfully while lifting win rate, because you're no longer fading pure stretch, you're fading stretch that's already losing momentum underneath.
Mean reversion beats trend following in four conditions: ranges with ADX under 20, post-event exhaustion after FOMC or NFP once the initial spike stalls, low-ATR sessions where breakouts keep failing, and instruments with strong overnight mean pull like index futures reverting to prior settlement. Outside those, you're fading a trend — and trends don't care how stretched your z-score says they are.
Ready to trade funded capital?
Choose your path — Instant Accounts, One-Step or Two-Step Challenges — from just $23, with up to $300,000 in funded capital.
Choose your challengeRSI mean reversion drawdown: why one blown range costs forty wins
The math is brutal: one unstopped RSI fade at -35R erases roughly 44 winning trades booked at 0.8R apiece. That's not a hypothetical — it's the arithmetic of every mean reversion strategy that skips the stop loss because "it always comes back." Until the one time it doesn't.
The unstopped fade and the shape of a catastrophic loss
Run the numbers. Forty wins at 0.8R = +32R. One loss at -35R = -35R. Net: -3R, and that's after forty correct calls. This is the defining shape of an rsi mean reversion strategy drawdown when there's no stop loss attached — a long, flat, gently rising equity curve followed by a cliff. The fade trader doesn't bleed out slowly like a bad trend follower who takes twenty small -1R losses in a row. The fade trader dies once, in a single candle, usually the one where they added to the position because "it's even more oversold now."
What a hard stop plus a trend filter does to the equity curve
Two fixes turn this from a coin-flip against catastrophe into a real edge:
- Hard stop at the statistical extreme. If you're fading RSI(14) below 20, your stop lives at the level where RSI has never gone below in the lookback period you tested — not at a round number, not at "where I feel uncomfortable." Cap the loss at 2-3R, full stop, no averaging in.
- Directional filter that forbids fades against a strong regime. No shorts when price sits above a rising 200-period mean and ADX is above 25. No longs on the mirror setup. This single rule kills the trade that would have been your -35R disaster, because it never lets you enter it.
Add both and the equity curve stops looking like a staircase to a trapdoor. It looks like what mean reversion is supposed to look like: high win rate, small individual losses, boring in the best way.
When mean reversion fails in trending markets
So when do mean reversion strategies fail in trending markets? Precisely when ADX is rising through 25 and you're still selling every push higher because RSI says "overbought." At that point you're not fading a stretched market — you're systematically shorting the strongest instrument on the board, against a trend that has real institutional flow behind it. Is mean reversion profitable in that regime? No. It's a losing game dressed up in a high win rate right up until it isn't.
This is also exactly why max drawdown and daily loss limit rules on a challenge account matter more for fade traders than for anyone else. A 5% max DD rule doesn't punish the forty small wins — it punishes the one unstopped fade that was always going to happen eventually. Build the hard stop and the trend filter into the system itself, and the daily loss limit becomes a rule you never test.
Momentum traps: the three tells before you get filled at the extreme
Momentum trap, defined in one sentence
Momentum trap meaning: a breakout that looks like continuation, fills the late buyers right at the extreme, and reverses through the broken level before the position ever works — turning what should've been a trend trade into an instant loss against you. It's the mirror image of the setup we just covered, and it's the reason a Donchian channel breakout that looks clean on the daily chart can still bust a challenge account inside one session.
You don't need to predict the reversal. You need to recognize the three tells that show up before the fill, not after.
Tell 1: volume divergence into the new high
Price prints a fresh high (or low) but volume on that final leg is lower than the volume that built the prior leg. That's distribution into strength, not accumulation — the move is running on fewer participants, which means fewer hands left to push it further. On CME futures this shows up plainly in the volume profile; on retail FX/CFD feeds you're reading tick volume, which is noisier but still directional enough to flag the divergence.
Tell 2: ATR stretched 2×+ beyond the average leg
Measure the current leg against your ATR percentile over the last 100 bars. If the leg pushing to the new extreme has already run more than 2× the average leg size for that instrument's recent regime, you're not looking at early momentum anymore — you're looking at the exhaustion phase of it. This is the same ATR percentile read from the intro's regime filter, just applied at the leg level instead of the regime level. A leg that's already stretched two standard deviations past normal has done most of its work; the reward left for a late entry is thin, and the risk of reversion is fat.
Tell 3: the failed retest
This is the tell that actually triggers a trade. Price breaks the level, pulls back to retest it — first attempt holds, second attempt doesn't. When the retest fails to hold the broken level twice, the breakout is dead and you've got your entry for the fade.
That's the entire momentum reversal trading strategy in practice: you don't fight the first breakout, and you don't guess the top. You wait for volume divergence plus an over-extended ATR leg to flag the setup, then you wait again for the failed retest to confirm it, and you enter counter-trend with your stop placed above the extreme print — the one point on the chart the market has already proven it won't reclaim twice.
- Entry: on confirmed second-attempt failure at the retest, not on the first touch
- Stop: above (or below) the extreme, not above the round number — the round number gets hit first
- Filter: only take the fade if Tell 1 and Tell 2 both fired before Tell 3 — one tell alone is noise
Stop logic by strategy: three signals, three completely different stops
Your stop isn't a fixed distance — it's a definition of "wrong," and that definition changes completely depending on which trade you're running. A breakout stop marks structure invalidation. A momentum stop trails to protect an outlier. A mean reversion stop marks a statistical extreme. Use one stop rule for all three and you'll bleed on two out of three setups before you even get to your edge.
Structure invalidation for breakouts
A breakout trade is only valid while the level it broke stays broken. Your stop goes back on the far side of that structure — the old resistance-turned-support, the range low, the failed swing high — not at a round number, not at a fixed pip count. If price trades back through the level with any conviction, the breakout thesis is dead regardless of how many pips you're down. This is the cleanest stop logic of the three because the market tells you exactly where "wrong" is: it's the line it just crossed.
Trailing stops for momentum continuation
Momentum trades exist to capture outliers, so cutting one early on a tight stop defeats the entire premise. A trailing stop — commonly set at 2–3x ATR behind price, or trailed under the prior swing low on a pullback structure — lets the trend do the work while still protecting gains if the move exhausts. The mistake we see constantly across evaluations: traders trail too tight on the first pullback, get stopped on normal noise, then watch the trend continue without them. A trailing stop needs room proportional to the instrument's own volatility, not your comfort level.
Statistical extremes for mean reversion
A fade is wrong when the deviation itself breaks its historical pattern — not when a nearby support level gives way. If you're fading a 2.5 standard deviation move from the mean, your stop sits beyond the level where that deviation would become a 3.5+ SD event, because at that point you're no longer trading a statistical outlier, you're trading a regime change. This stop is intentionally close to the extreme print, because the entire edge depends on the extreme holding.
| Strategy | Stop logic | Typical placement | What invalidates it |
|---|---|---|---|
| Breakout | Structure invalidation | Back beyond the broken level | Price reclaims the level with volume |
| Momentum | Trailing stop | 2–3x ATR behind price, or below prior swing | Trend structure breaks / ATR contracts sharply |
| Mean reversion | Statistical extreme | Just beyond the deviation threshold (e.g. 3+ SD) | Deviation extends past historical distribution |
The classic error is running a fixed 20-pip stop across all three. On the momentum trade it's suicide — you'll get trailed out on the first retracement of a move that runs another 200 pips. On the fade it's reckless — 20 pips might sit well inside the normal noise band of the extreme, giving you zero margin before the statistical thesis is even tested. Stop loss placement by strategy isn't a detail you bolt on after finding your entry — it's part of the entry.
Regime switching: what you gain and what it costs you
Pros
- You stop taking the right trade in the wrong market — the single largest source of avoidable losses for traders who already know both playbooks
- Two uncorrelated return streams smooth the equity curve, which matters more under a daily loss limit than any single-strategy win rate
- Explicit numeric thresholds (ADX, ATR percentile, Hurst) remove the discretionary 'this feels like a range' call that ruins fade traders
- Momentum mode captures the outlier days that clear a 10% profit target; mean reversion mode keeps the account alive between them
Cons / risks
- Two systems means two sets of rules, two stop logics and twice the execution errors while you're learning them
- Regime measures lag — Hurst and ATR percentile confirm a shift after it has started, so you will always give back part of the transition
- Hysteresis reduces whipsaw but also means you sit in the wrong mode for a few bars after the market has genuinely changed
- The no-regime zone can last weeks, and standing down is harder than it sounds when a challenge has a time limit
Ready to trade funded capital?
Choose your path — Instant Accounts, One-Step or Two-Step Challenges — from just $23, with up to $300,000 in funded capital.
Choose your challengeFrequently Asked Questions
What is the difference between momentum and mean reversion?+
Momentum bets price keeps moving in the direction it's already going, while mean reversion bets an extended move snaps back toward its average. Momentum thrives on trending regimes — breakouts, NFP follow-through, sustained trend legs on XAUUSD or US100. Mean reversion thrives on range-bound, choppy conditions where price oscillates around a mean without follow-through. Neither is universally 'better' — the edge comes from matching the strategy to the current regime, not picking a side and forcing it on every session.
What signals show a market shifting from momentum to mean reversion?+
A falling ADX below roughly 20-25 combined with contracting ATR percentile is the clearest tell that trend energy is draining and range conditions are taking over. Watch for lower highs on momentum oscillators even as price makes fresh extremes (bearish/bullish divergence), narrowing Bollinger Bands, and a Hurst exponent or variance ratio dropping toward 0.5 or below. When two or three of these align, shift position sizing toward fade setups at range extremes and tighten trend-following stops rather than adding to breakout risk.
How does a mean reversion strategy work and when beats trend following?+
Mean reversion fades extended moves back toward a statistical average — typically entering when RSI, z-score, or Bollinger Band deviation hits an extreme, then targeting the mean itself. It beats trend following in low-volatility, range-bound regimes where breakouts repeatedly fail and price respects a channel — think overnight sessions on indices or consolidation phases on gold before a catalyst. Trend following wins during sustained directional moves; mean reversion wins in the chop between them, which is why regime detection matters more than either strategy alone.
Is mean reversion trading actually profitable long term?+
Mean reversion can be profitable, but it produces a high win rate with small average wins and occasional large losses when a range breaks — the opposite payoff profile of trend following. One missed regime shift, where you keep fading a move that turns into a real breakout, can erase months of small wins if stops aren't strict. Profitability depends less on the setup itself and more on disciplined stop placement and knowing when the range has genuinely broken versus just extended further.
What is a momentum trap in trading?+
A momentum trap is a false breakout that pulls late trend-followers in right before price reverses, usually at a liquidity extreme where stops get run and market makers fill against the crowd. Tells include a breakout on thinning volume, a spike that immediately closes back inside the prior range, and RSI or MACD showing divergence at the exact level price is breaking. Traders who chase the extreme without confirmation — a retest holding, or volume expanding through the level — are the ones who get filled right at the trap's peak.
How do you set stops on an RSI mean reversion strategy?+
Set stops beyond the recent swing extreme or a fixed ATR multiple past your entry — never at the round number, since that's exactly where a failed reversion runs stops before continuing. RSI mean reversion strategies get hurt worst when a range breaks into a real trend, so a hard invalidation level (structure-based, not just 'RSI un-extreme') protects against catastrophic drawdown. Many traders also add a time-stop: if the reversion hasn't triggered within a set number of candles, exit — a stalled fade often means the regime already shifted to momentum.
What ADX and ATR levels signal a regime switch?+
ADX below roughly 20-25 with ATR percentile in the bottom third of its recent range typically signals a mean-reversion regime, while ADX climbing above 25-30 alongside expanding ATR signals momentum taking control. A Hurst exponent above 0.55 or a variance ratio above 1 supports trending behavior; below 0.45-0.5 supports reversion. No single threshold is bulletproof — combine two or three of these with price structure (higher highs/lows vs. range boundaries) before flipping strategy mode, since single-indicator regime calls whipsaw constantly around the threshold.
Do momentum and mean reversion behave differently on gold and crypto?+
XAUUSD tends to trend hard around macro catalysts (Fed decisions, NFP) but chops heavily between them, making it a strong regime-switching candidate. US100 shows cleaner intraday momentum during US session hours and reverts more predictably overnight. BTC perpetuals run momentum-driven during high-funding, high-volume moves but mean-revert violently after liquidation cascades, since forced closes create sharp overextensions that snap back. The common thread: session timing and catalyst proximity matter as much as the asset class itself when choosing which mode to run.
Which strategy survives a 5% max drawdown evaluation better?+
Mean reversion strategies generally protect a tight max drawdown limit better because losses are typically smaller and more frequent, giving cleaner control over daily loss limits — but only if stops are strict, since one unmanaged breakout can blow through 5% in a single trade. Momentum strategies risk fewer, larger losing trades that can eat drawdown fast if a breakout fails, but they also produce the bigger wins that hit profit targets quicker. On a Two-Step Challenge, many traders blend both — mean reversion for consistency, momentum for the occasional outsized push toward target.
Can you trade momentum and mean reversion at the same time?+
Running both is possible and common among systematic traders, but you need to size them so they don't secretly correlate into one combined loss on the same move. The practical fix is capping total exposure per instrument regardless of which strategy triggers, and confirming the two systems are actually reading different regimes — not both flat, or both long, at the same time on correlated pairs like XAUUSD and DXY. Backtest the combined equity curve, not each strategy in isolation, since overlapping drawdowns are the real risk.
Written by
Marcel Hambálek
Senior Trader, For Traders
Marcel trades Futures and Forex day-trading setups on funded accounts and writes about the executional details most traders skip — order types, slippage, session timing, platform quirks on MT5 and NinjaTrader. Pragmatic, mechanics-first, no fluff.
Follow on LinkedInReady to trade funded capital?
Choose your path — Instant Accounts, One-Step or Two-Step Challenges — from just $49, with up to $300,000 in funded capital.
Choose your challengeTrade up to $300,000
Choose challenge